
Why Florida Auto Insurance Costs So Much—And What You Need to Know
Auto insurance Florida is required by law, but it’s also among the most expensive in the nation. Here’s what you need to know:
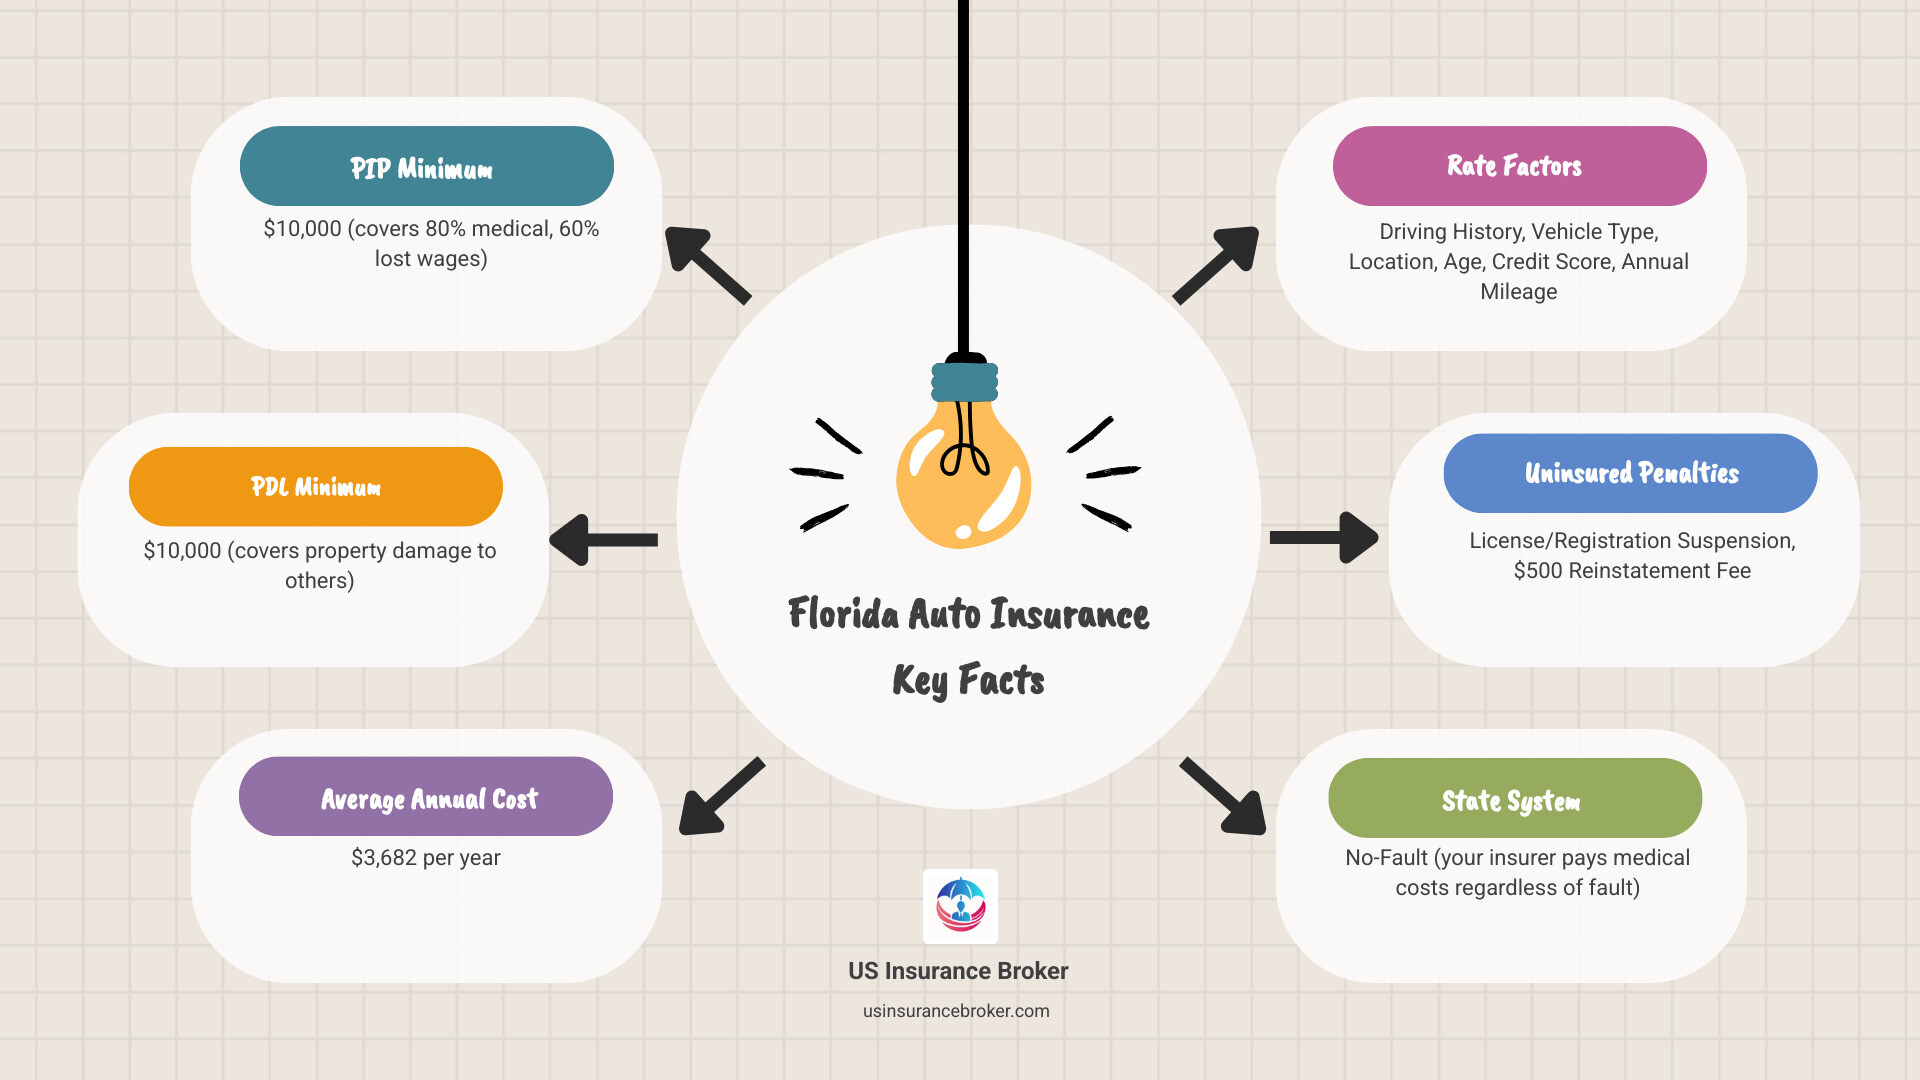
- Minimum Required Coverage: $10,000 Personal Injury Protection (PIP) + $10,000 Property Damage Liability (PDL)
- Average Annual Cost: $3,682 (68% higher than the national average)
- Why It’s Expensive: High uninsured driver rates, frequent hurricanes, no-fault law, and litigation costs
- Penalties for Driving Uninsured: License suspension, registration suspension, and reinstatement fees up to $500
Florida’s auto insurance landscape is complicated by its no-fault system, where your own insurance covers your initial medical bills. However, the required minimums of $10,000 in PIP and $10,000 in PDL are often far too low for a serious accident, where costs can quickly exceed these limits.
Florida drivers pay significantly more than the national average, but understanding what drives these costs can save you thousands annually. This guide breaks down Florida’s unique requirements, the coverages you actually need, how to compare policies, and proven strategies to lower your premiums without sacrificing protection.
I’m William Kane II, a licensed Florida insurance broker and owner of US Insurance Broker. I’ve spent years helping drivers steer auto insurance Florida options to secure comprehensive coverage at competitive rates. This guide will give you the clarity and confidence to make the right choice.
Auto insurance Florida terms to remember:
- Auto Insurance for High-Risk Drivers in Florida
- Cheapest Insurance in Florida for Young Drivers
- Clearwater Auto Insurance Quotes
Understanding Florida’s Auto Insurance Requirements
Florida operates under a “no-fault” system, meaning your own insurance company pays for your initial medical expenses after an accident, regardless of who is at fault. This system is designed to streamline minor claims but comes with specific mandatory requirements.
You must maintain continuous insurance coverage for your vehicle’s entire registration period, even if it’s not being driven. If you cancel your insurance, you must surrender your license plates first to avoid penalties like license suspension and hefty reinstatement fees.
For official rules, consult the Florida Insurance Requirements.
Mandatory Auto Insurance Florida Requirements: PIP & PDL
To register a vehicle with four or more wheels in Florida, you need proof of two coverages:
- Personal Injury Protection (PIP): As the core of the no-fault system, PIP covers your own medical bills and other losses. The $10,000 minimum covers 80% of necessary medical expenses (if treated within 14 days), 60% of lost wages, and a $5,000 death benefit.
- Property Damage Liability (PDL): This covers damage you cause to someone else’s property, like their car or a fence. The minimum required is $10,000 per accident.
These minimums are dangerously low by today’s standards. A single ER visit or a minor multi-car accident can easily surpass $10,000, leaving your personal assets vulnerable. We strongly advise carrying higher limits.
Penalties for Driving Uninsured in Florida
Driving without the required auto insurance Florida carries serious legal consequences:
- License and Registration Suspension: Your driving privilege and vehicle registration can be suspended for up to three years.
- Reinstatement Fees: You’ll have to pay up to $500 to reinstate your license and registration, on top of buying new insurance.
- SR-22/FR-44 Requirement: For certain violations, you may need an SR-22, a certificate proving you have liability coverage. More severe infractions like a DUI may require an FR-44, which mandates much higher liability limits.
Florida’s Financial Responsibility Law also requires you to carry Bodily Injury Liability (BIL) if you cause an accident with injuries or receive certain serious traffic citations.
Decoding Your Policy: A Complete Guide to Coverage Options
Your auto insurance Florida policy declaration page summarizes your coverages, limits, and deductibles. Understanding these terms is key:
- Deductibles: The amount you pay out-of-pocket before your insurance kicks in for claims like collision or comprehensive. A higher deductible usually means a lower premium, but be sure you can afford it in an emergency.
- Coverage Limits: The maximum amount your insurer will pay for a covered loss. For example, a “25/50/25” liability policy provides $25,000 per person for bodily injury, $50,000 per accident for bodily injury, and $25,000 for property damage.
Here’s a breakdown of key coverage types:
| Coverage Type | What It Covers | Mandatory in Florida? |
|---|---|---|
| Personal Injury Protection (PIP) | Medical expenses, lost wages, and death benefits for you and your passengers, regardless of fault. | Yes ($10,000 minimum) |
| Property Damage Liability (PDL) | Damage you cause to someone else’s property (e.g., another car, fence, building). | Yes ($10,000 minimum) |
| Bodily Injury Liability (BIL) | Injuries you cause to other people in an accident. | No, unless you’ve caused an accident with injury/death or received certain citations (Financial Responsibility Law), or have a DUI conviction. Highly recommended. |
| Collision | Damage to your vehicle from an accident with another vehicle or object, or if you roll over. | No, but often required by lenders for financed/leased vehicles. |
| Comprehensive | Damage to your vehicle from non-collision events like theft, vandalism, fire, falling objects, or natural disasters (e.g., hurricanes, floods). | No, but often required by lenders for financed/leased vehicles. |
| Uninsured/Underinsured Motorist (UM) | Injuries and damages to you and your passengers if the at-fault driver has no insurance or not enough insurance. | No, but highly recommended due to Florida’s high rate of uninsured drivers. |
| Medical Payments (MedPay) | Medical expenses for you and your passengers, regardless of fault, can supplement PIP. | No. |
Core Coverages: Liability, Collision, and Comprehensive
These three are the pillars of comprehensive auto protection:
- Bodily Injury Liability (BIL): While not always mandatory, we strongly recommend BIL. It protects your assets if you’re at fault for an accident that injures others. Without it, you could be sued personally, putting your savings and future earnings at risk.
- Collision Coverage: This covers damage to your vehicle from a collision with another car or object. Lenders almost always require it for financed or leased vehicles.
- Comprehensive Coverage: This is your shield against non-collision events like theft, vandalism, fire, and natural disasters like hurricanes—a must-have in Florida, especially for newer or financed cars.
For more in-depth information, visit our page: More info about auto insurance.
Florida-Specific Coverages: PIP, MedPay, and Uninsured Motorist (UM)
Florida’s legal framework gives special importance to these coverages:
- Personal Injury Protection (PIP): Your first line of defense for medical bills, PIP covers 80% of necessary medical expenses (up to $10,000 for an emergency medical condition) and 60% of lost wages, regardless of fault. Initial treatment must be within 14 days of the accident.
- Medical Payments (MedPay): This optional coverage helps pay for medical expenses not covered by PIP, like the remaining 20% of your bills or your deductible.
- Uninsured/Underinsured Motorist (UM): Crucial in a state where 1 in 5 drivers is uninsured, UM pays for your injuries and damages if the at-fault driver has no insurance or not enough. You can choose between two types:
- Stacked UM: Combines the UM limits for all vehicles on your policy, offering a higher total limit. For example, two cars with $50,000 UM coverage each would give you $100,000 in stacked coverage. This is the default in Florida unless you reject it in writing.
- Non-stacked UM: Your coverage limit is fixed per accident, regardless of how many vehicles are on your policy.
We often recommend stacked UM for the most robust protection.
The Cost of Florida Car Insurance and How to Save
The cost of auto insurance Florida can be a shock. In 2024, the average cost was $3,682, a staggering 68% higher than the national average. This premium price tag is due to a blend of factors, including our unique weather, busy roads, and specific state laws.
Understanding these costs is the first step to saving money. For a detailed look at prices across the state, see our guide on Car Insurance in Florida Average Price.
What Factors Influence Your Insurance Premiums?
Insurers assess various risk factors to determine your premium. Here’s what they look at:
- Driving History: Accidents, tickets, and DUIs significantly increase rates. A clean record leads to substantial savings over time.
- Vehicle Type: The make, model, and value of your car matter. Expensive cars, sports cars, or those with high repair costs are generally more expensive to insure.
- Location (ZIP Code): Urban areas like Tampa and St. Petersburg often have higher rates due to more traffic, accidents, and theft. Some counties, like Hillsborough, may require pre-insurance inspections.
- Age and Gender: Younger, less experienced drivers face much higher premiums. Rates tend to decrease with age and experience, and married individuals often see lower rates.
- Credit History: In Florida, a better credit score can lead to significantly lower insurance premiums.
- Annual Mileage: Driving more, especially for a long commute or business, can increase your rates.
Finding the Cheapest Auto Insurance Florida: Discounts and Tips
Despite high average rates, there are many ways to find affordable auto insurance Florida. We help clients uncover every possible discount:
- Multi-Policy (Bundling) Discount: One of the easiest ways to save is by bundling your auto policy with home, renters, or boat insurance.
- Good Driver Discount: A clean driving record is often rewarded. Safe driver programs that track your habits via an app can also lead to savings.
- Good Student Discount: Young drivers on your policy with good grades may qualify for a discount.
- Vehicle Safety Features Discount: Cars with anti-lock brakes, airbags, and anti-theft devices often qualify for lower premiums.
- Other Common Discounts: Ask about savings for low mileage, insuring multiple cars, paying your premium in full, or setting up automatic payments.
- Increase Your Deductible: Raising your deductible will almost always lower your premium, but make sure you can afford the higher out-of-pocket cost.
- Review Your Coverage: For older, paid-off vehicles, you might consider dropping collision and comprehensive coverage if the cost outweighs the car’s value.
- Shop Around: Prices vary widely. We recommend comparing quotes regularly, especially at renewal or after a life change.
For more strategies, visit our page on Best Price Car Insurance Florida.
Navigating Claims, Special Cases, and Finding Resources
Navigating an accident or unique insurance situation can be stressful, but we’re here to help.
If you’re in a minor accident, stay calm, exchange information, take photos, and contact law enforcement if possible. Notify your insurer promptly. You have the right to choose your own repair shop. The insurer must ensure repairs use parts of equal quality to the originals. Some counties, like Hillsborough, may require pre-insurance inspections for physical damage coverage.
Insurance for Unique Drivers: Students, Military, and New Residents
Your insurance needs can change with your circumstances. We help ensure your coverage fits your situation:
- Non-Residents and College Students: If you move to Florida for work, enroll a child in a public school, or live here for over 90 days as a student, you must get a Florida registration and insurance policy (PIP and PDL).
- Military Personnel: If you’re stationed out-of-state with a Florida-titled vehicle, you may be exempt from continuous coverage requirements by submitting your orders.
- Financed or Leased Vehicles: Lenders will require you to carry full coverage (liability, collision, and comprehensive) to protect their investment. They cannot, however, force you to use a specific insurer. Consider GAP insurance to cover the difference between your loan balance and the car’s value if it’s totaled.
- Motorcycles and Business Use: Motorcycles need a separate policy (PIP does not apply). Using your personal vehicle for business usually requires commercial auto insurance, as personal policies often exclude it.
For drivers with a challenging record, our team specializes in finding solutions. Learn more at Auto Insurance for High Risk Drivers Florida.
After an Accident: Filing a Claim and Resolving Disputes
Knowing the claims process brings clarity after an accident.
- Notify Your Insurer Promptly: Report the accident as soon as possible. For PIP claims, insurers generally must pay within 30 days of notification.
- Total Loss Determination: If repair costs exceed your car’s actual cash value (ACV), it may be declared a “total loss.” Your settlement will be based on the ACV, which is the cost to replace your vehicle with a similar one, accounting for depreciation.
- Dispute Resolution: If you disagree with your insurer’s assessment, Florida offers several options:
- Comparative Negligence: Fault can be shared in an accident, and your damages may be reduced by your percentage of fault.
- Appraisal Clause: Your policy may include an appraisal clause to resolve disagreements over the damage amount, using neutral appraisers.
- Mediation: Florida offers a voluntary mediation program for certain claims to help both sides reach a settlement with a neutral mediator.
For more information, the state provides the Official Florida Automobile Insurance Toolkit.
Frequently Asked Questions about Auto Insurance Florida
Here are answers to some of the most common questions we hear about auto insurance Florida.
How much Bodily Injury Liability (BIL) coverage is recommended in Florida?
While not always mandatory to register a car, we highly recommend Bodily Injury Liability (BIL). If you’re at fault in an accident that injures someone, BIL protects your personal assets from lawsuits. State minimums are dangerously low.
We suggest carrying at least $100,000 per person / $300,000 per accident in BIL. This provides significantly better protection against the high costs of a serious accident. Without it, an injured party can sue you directly for damages, putting your savings and property at risk.
What is the difference between stacked and non-stacked Uninsured Motorist (UM) coverage?
Uninsured Motorist (UM) coverage is crucial in Florida, where many drivers are uninsured. It protects you if you’re hit by a driver with no insurance or not enough. The difference is how the limits apply:
- Stacked UM: This combines the UM limits for all vehicles on your policy. For example, if you have two cars with $50,000 in UM coverage each, your stacked limit becomes $100,000. This is the default in Florida unless you reject it in writing.
- Non-stacked UM: Your UM coverage limit is fixed per accident, regardless of how many vehicles are on your policy.
While non-stacked UM is slightly cheaper, the added protection of stacked UM is a worthwhile investment on Florida’s roads.
Does my Florida auto insurance policy cover a rental car?
Usually, yes, but the specifics vary. Your personal auto insurance Florida policy’s liability, collision, and comprehensive coverages typically extend to a rental car in the U.S. and Canada, but you’re still responsible for your deductible.
Before renting, consider these points:
- Rental Company Insurance: Rental agencies offer their own expensive coverage, like a Loss Damage Waiver (LDW).
- Credit Card Benefits: Many credit cards offer secondary rental car insurance, which applies after your personal auto policy pays out.
- Rental Reimbursement Coverage: This is an optional add-on to your policy that pays for a rental car while your car is being repaired after a covered claim. It’s different from coverage for a vacation rental.
Always check with your insurer before renting to understand your exact coverage.
Conclusion: Partnering with an Expert for Your Florida Insurance Needs
Navigating auto insurance Florida can feel like driving through a labyrinth, but it doesn’t have to be. We’ve seen that understanding our state’s unique requirements, from the no-fault system to mandatory PIP and PDL, is just the starting point. Going beyond these minimums with adequate liability, collision, comprehensive, and especially Uninsured Motorist coverage, is crucial for truly protecting your financial well-being in our busy state.
We’ve also explored how factors like your driving history, vehicle, and even your ZIP code (from Tampa to St. Petersburg, Hillsborough River to the Gulf Coast) influence your premiums. But remember, there are plenty of ways to save, from bundling policies to leveraging good driver discounts.
At US Insurance Broker, we believe that insurance should be simple, secure, and reliable. As a Florida-based broker, we pride ourselves on our local focus, helping our neighbors across Tampa, Clearwater, St. Petersburg, and the entire Gulf Coast find coverage that makes sense for their unique lives. We’re here to offer personalized advice, ensuring you understand your options and feel confident in your choices.
Don’t let the complexities of auto insurance Florida leave you feeling unprotected or overpaying. Let us help you find the right coverage at the right price, so you can enjoy the beautiful Florida roads with peace of mind.
Get a personalized auto insurance quote today and find the difference a local expert can make!