
Why Understanding Auto Insurance for High-Risk Drivers Florida Matters Now
Auto insurance for high risk drivers florida is a reality many Floridians face after a DUI, multiple speeding tickets, or at-fault accidents. Being labeled “high-risk” means insurers see you as more likely to file a claim, which leads to higher premiums.
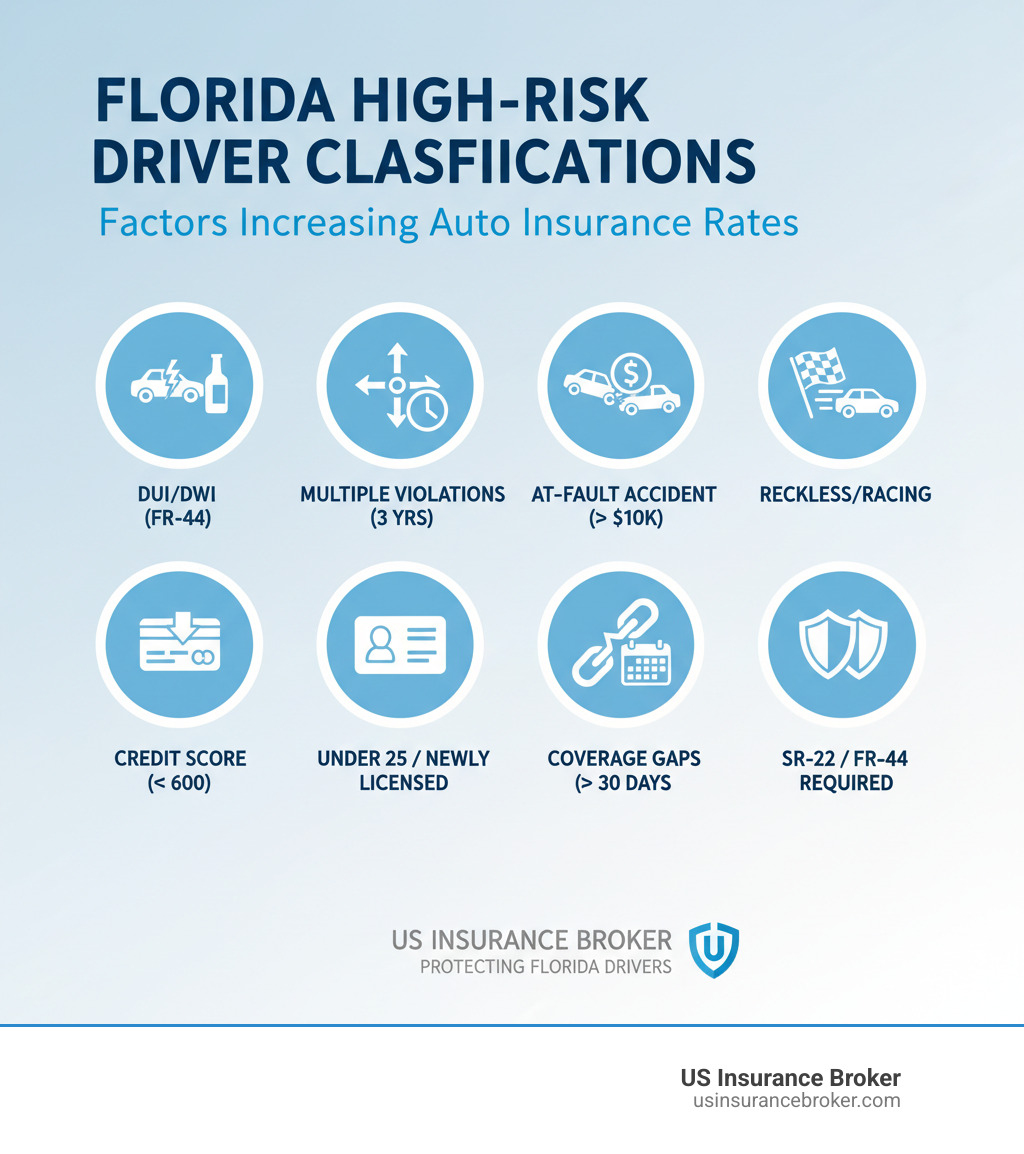
You may be classified as high-risk if you have:
- A DUI/DWI conviction
- Multiple speeding tickets
- At-fault accidents
- Reckless or distracted driving citations
- A poor credit score
- A lapse in insurance coverage
High-risk drivers in Florida pay an average of $3,160 per year, a 47% increase over the $2,148 average for drivers with clean records. A single at-fault accident can spike your premiums by 45%, while a DUI can increase rates by up to 88%.
Florida’s insurance market is tough, with some of the highest costs in the country. You must carry at least $10,000 in Personal Injury Protection (PIP) and $10,000 in Property Damage Liability (PDL). A DUI conviction requires an FR-44 certificate, proving you have even higher liability limits.
The good news? This status isn’t permanent. Most violations affect your rates for 3-5 years, and you can take steps to lower your premiums now.
I’m William Kane II, owner of Forever Florida Insurance, and I’ve helped countless Florida drivers steer the complexities of auto insurance for high risk drivers florida. By comparing rates across 30+ carriers, we find affordable, comprehensive coverage for your specific situation. With access to both standard and non-standard insurers, I can help you find a policy even when others say no.
Important auto insurance for high risk drivers florida terms:
- best price car insurance florida
- car insurance in florida average price
- auto insurance lehigh acres fl
What Defines a High-Risk Driver in Florida?
When insurance companies review your application for auto insurance for high risk drivers florida, they analyze your driving history to predict how likely you are to file a claim. If your record suggests a higher risk, you’ll be labeled high-risk, which results in higher premiums.
Fortunately, this status isn’t permanent. Minor violations like a speeding ticket typically affect your rates for 3 to 5 years. A major violation like a DUI conviction has a longer impact, with insurers considering it for 5 to 10 years when setting rates.
Factors That Classify You as High-Risk
Several factors can place you in the high-risk category:
DUI or DWI Conviction: This is the most serious offense, immediately flagging you as high-risk and triggering Florida’s FR-44 requirement for higher liability limits.
Multiple Speeding Tickets: A pattern of speeding tells insurers you’re a habitual risk-taker.
At-Fault Accidents: If you’ve caused an accident, especially one with significant damage or injuries, your insurer will view you as more likely to have another. Even a single personal injury protection (PIP) claim can raise red flags due to Florida’s history with PIP fraud.
Reckless Driving or Racing: These major violations demonstrate a willful disregard for safety and are a quick way to see your insurance rates skyrocket.
Poor Credit Score: Florida allows insurers to use credit-based scores to set rates. A score below 600 can increase your premiums, even with a clean driving record.
Young or Inexperienced Drivers: Statistically, teen drivers and newly licensed adults have higher accident rates, leading to higher initial premiums.
Lapse in Coverage: Going 30 days or more without insurance suggests instability to insurers, increasing your risk profile.
SR-22 or FR-44 Certificate: If the state mandates you file one of these certificates, you are automatically considered high-risk. You can learn more about Florida auto insurance requirements on our main page.
How Your Driving Record Impacts Your Status
Your driving record is a key factor for insurers. Recent violations carry the most weight. A single at-fault accident can increase your premiums by 45% or more. Multiple accidents can lead to even steeper increases.
In Florida, insurers are particularly wary of multiple PIP claims. The state’s no-fault system has been exploited by fraud, so even legitimate claims are scrutinized. Additionally, Florida takes distracted driving seriously, and a citation will add points to your record. You can review Florida’s distracted driving laws to understand what to avoid.
The path out of high-risk status is to drive safely and pay your premiums on time. As violations age and fall off your record, your rates will gradually decrease.
The Cost of Auto Insurance for High-Risk Drivers Florida
The reality is that auto insurance for high risk drivers florida costs more. While a Florida driver with a clean record pays around $2,148 per year, high-risk drivers face an average of $3,160 annually—a 47% increase.
The severity of the violation matters. A single at-fault accident might increase your premiums by 45%, while a DUI conviction can cause an 88% spike, with average rates around $4,713 per year.
The good news is that rates vary significantly between insurance companies. Some insurers specialize in high-risk drivers, while others may not offer coverage at all. Shopping around is essential to find the best rate. You can learn more about the pricing landscape on our Car Insurance in Florida: Average Price page.
Understanding SR-22 and FR-44 Requirements
Many high-risk drivers must file an SR-22 or FR-44. These are not insurance policies but Certificates of Financial Responsibility that your insurer files with the state to prove you have coverage. You must typically maintain them for three consecutive years.
- The SR-22 is often required for violations like driving without insurance. It proves you have at least Florida’s minimum liability coverage.
- The FR-44 is stricter and tied almost exclusively to DUI/DWI convictions. It requires much higher liability limits: $100,000 per person, $300,000 per accident, and $50,000 for property damage. These higher limits mean higher premiums.
While the filing fee is small, the real cost comes from the increased premiums. Finding affordable coverage that meets these requirements is possible with the right strategy. Check out our guide to Best Price Car Insurance Florida for tips.
Average Costs for Auto Insurance for High-Risk Drivers Florida
Here are some average annual costs in Florida. Your specific rate will depend on your location, vehicle, and driving history.
- Clean Record: $2,148
- After a Speeding Ticket: $2,426 (13% increase)
- After an At-Fault Accident: $2,558 (19% increase)
- After a DUI: $4,713 (120% increase)
Teen drivers face high rates due to inexperience, often paying thousands annually even with a clean record. Similarly, drivers with poor credit can expect to pay significantly more than those with good credit. The variation between insurance companies can be substantial, with potential savings of over $1,000 per year for the same driver profile, highlighting the importance of comparing quotes.
While minimum coverage is cheaper, full coverage (including collision and comprehensive) offers crucial protection for your vehicle and is often a wise investment for high-risk drivers who can’t afford another major financial setback.
How to Lower Your Insurance Premiums
Being labeled high-risk doesn’t mean you’re stuck with high premiums forever. You have the power to lower your auto insurance for high risk drivers florida costs through proactive steps and a commitment to safe driving.
Actionable Steps for Immediate and Future Savings
- Shop Around: Comparing quotes from multiple providers is the fastest way to find a lower rate. Different companies assess risk differently, so one may offer a much better price than another.
- Take a Defensive Driving Course: A state-approved course can provide an immediate discount and teaches skills to prevent future incidents.
- Improve Your Credit Score: In Florida, a better credit score can lead to lower insurance premiums. Pay bills on time and reduce debt to see improvements.
- Ask About Discounts: Inquire about all available discounts, such as bundling policies, good student discounts, or savings for vehicle safety features.
- Increase Your Deductible: Choosing a higher deductible (e.g., $1,000 instead of $500) will lower your monthly premium. Just ensure you can afford the out-of-pocket cost if you file a claim.
- Consider Your Vehicle: Cars with high safety ratings and lower repair costs are cheaper to insure.
- Use Telematics Programs: Many insurers offer programs that track your driving habits via an app. Safe driving can earn you significant discounts based on your actual behavior.
For business owners facing similar challenges, these principles also apply. Learn more on our Business Insurance: Commercial Auto Insurance page.
Finding the Right Coverage for Auto Insurance for High-Risk Drivers Florida
Finding affordable coverage is about balancing price with adequate protection.
- Work with Independent Insurance Agents: Unlike agents tied to one company, we can shop your profile across multiple carriers, including specialty insurers that focus on the high-risk market. This saves you time and often results in better rates.
- Compare Multiple Carriers: High-risk rates vary dramatically. Getting at least three to five quotes is essential to ensure you’re not overpaying.
- Go Beyond Minimum Requirements: Florida’s minimums—$10,000 in PIP and $10,000 in PDL—are often insufficient in a serious accident. Consider adding bodily injury liability and uninsured/underinsured motorist coverage to protect your assets from a major lawsuit. Higher limits provide crucial financial protection and peace of mind.
Our local expertise helps us tailor coverage for your specific needs. See how we approach local insurance in our Car Insurance New Port Richey, FL guide.
What to Do If You’re Denied Coverage
A denial letter for auto insurance for high risk drivers florida can be disheartening, but it’s not the end of the road. Florida has systems in place for this exact situation, and you have options to get the coverage you need to drive legally.
Florida’s Safety Net: The FAJUA Program
When private insurers say no, the Florida Automobile Joint Underwriting Association (FAJUA) serves as the state’s insurance safety net. It’s the “market of last resort,” designed to provide coverage to drivers who have been denied elsewhere.
To get FAJUA coverage, you must be a Florida resident with a vehicle registered in the state and apply through an authorized insurance agent. While FAJUA guarantees you can meet the state’s legal requirements, its policies are significantly more expensive than those on the private market.
FAJUA is a temporary solution. At Forever Florida Insurance, we exhaust all private market options first, using our network of carriers to find affordable auto insurance for high risk drivers florida before turning to FAJUA. Our Car Insurance Lehigh Acres, FL Guide offers more insights into navigating these situations.
The Consequences of Driving Uninsured in Florida
Driving without insurance in Florida is illegal and carries severe penalties that are far worse than any high-risk premium.
If caught, you face suspension of your driver’s license and vehicle registration for up to three years, with reinstatement fees starting at $150 and increasing for subsequent offenses. The state may also require you to file an FR-44 certificate, mandating much higher, more expensive liability coverage.
Most importantly, if you cause an accident while uninsured, you are personally liable for all damages and injuries. This can lead to lawsuits, wage garnishment, and financial ruin. The cost of a high-risk policy is minimal compared to the devastating risks of driving uninsured.
Frequently Asked Questions about High-Risk Insurance
When you’re dealing with auto insurance for high risk drivers florida, questions are normal. Here are answers to the most common ones we hear.
How long does a DUI affect my insurance in Florida?
A DUI has long-lasting effects. You’ll be required to maintain an FR-44 certificate for at least three consecutive years, which involves carrying much higher liability limits. Beyond that, most insurers will use the DUI to calculate your rates for 5 to 10 years. The criminal charge itself can remain on your driving record permanently unless it is expunged.
Can I get insurance if I’ve been denied by multiple companies?
Yes. If you’re denied by private insurers, you can get coverage through the Florida Automobile Joint Underwriting Association (FAJUA), the state’s assigned-risk pool. While FAJUA policies are more expensive, they ensure you can drive legally. Before resorting to FAJUA, an independent broker can check with specialty carriers that focus on high-risk drivers and may offer better rates.
What is the fastest way to lower my high-risk insurance rate?
The quickest way to save money is to shop around and compare quotes from multiple providers. Because each company assesses risk differently, you can find significant price variations for the same coverage. The second-fastest method is to complete a state-approved defensive driving course, as many insurers offer an immediate discount upon completion.
Let an Expert Steer Your High-Risk Insurance Needs
Finding affordable auto insurance for high risk drivers florida is achievable with the right strategy. Your high-risk status isn’t permanent. Every day you drive safely brings you closer to lower premiums and more options.
We understand that dealing with high insurance costs after a DUI or multiple tickets is stressful. A clean driving record moving forward is your most powerful tool for improving your rates.
At Forever Florida Insurance, we simplify insurance for Floridians in Tampa, Clearwater, St. Petersburg, and across the Gulf Coast. Florida’s market is tough, with high rates and strict requirements like FR-44 filings. Our local expertise makes a real difference.
Instead of spending hours calling different companies, let us do the work. We compare rates from over 30 carriers, including specialty insurers that focus on high-risk drivers. We know how to find the best rates and structure a policy that provides maximum coverage for your budget.
Don’t let a high-risk label leave you with overpriced insurance or, worse, driving uninsured. Get help with your auto insurance today and let us find a path forward. Your future on the road deserves expert guidance, and we’re ready to provide it.