
Why Homeowners Insurance in Pembroke Pines FL Costs More Than You Think
Homeowners insurance Pembroke Pines FL is significantly more expensive than both the state and national averages, and understanding why can save you thousands of dollars. Here’s what you need to know:
Quick Facts:
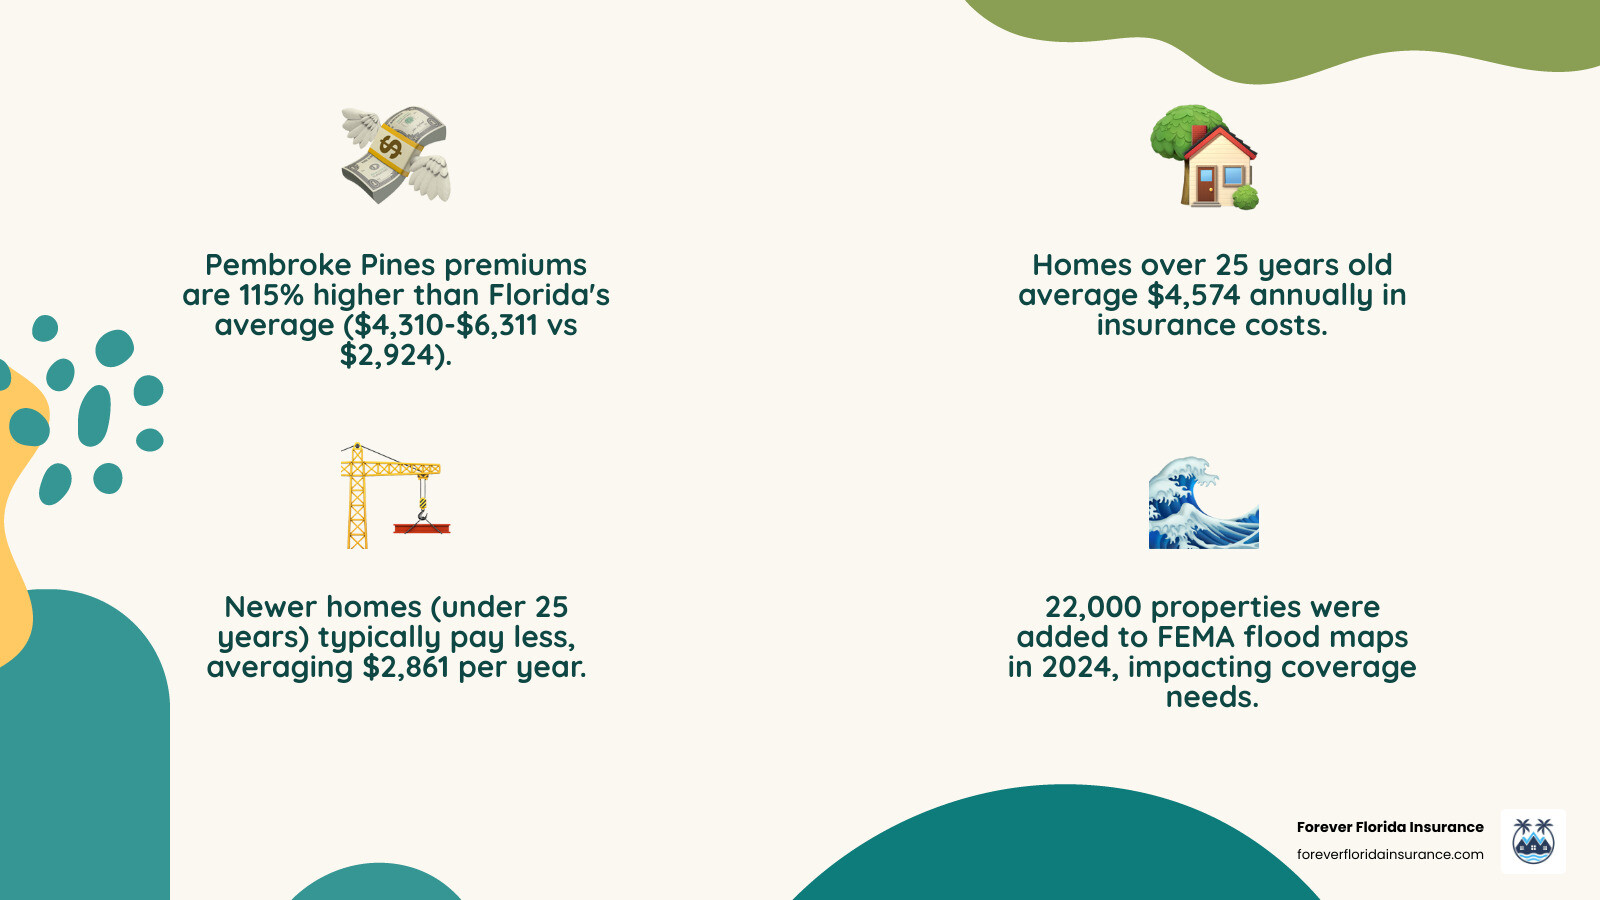
- Average annual cost in Pembroke Pines: $4,310 to $6,311
- Florida state average: $2,924
- Cost increase: 115% higher than state average
- Homes older than 25 years: Average $4,574/year
- Newer homes (under 25 years): Average $2,861/year
- Recent flood zone additions: 22,000 properties added to FEMA maps in 2024
Pembroke Pines is a beautiful place to call home, but living here comes with unique insurance challenges. The city sits in Broward County, where home insurance rates jumped 31% between 2022 and 2024. Between hurricane risks, updated flood zone maps, and aging homes, many residents are paying far more than they should—or worse, carrying coverage that won’t protect them when disaster strikes.
The reality is stark: if your home was built before 2001, you’re likely paying significantly higher premiums due to older construction standards. And if you’re one of the thousands of homeowners recently added to FEMA’s flood zone maps, you may need additional coverage that your standard policy doesn’t include.
I’m William Kane II, owner of US Insurance Broker and Forever Florida Insurance, and I’ve spent years helping Pembroke Pines homeowners steer Florida’s complex insurance market. My expertise in homeowners insurance Pembroke Pines FL comes from working directly with 30+ carriers to find the right coverage at the best rates for families just like yours.
In this guide, we’ll break down exactly what drives your premiums, what your policy actually covers (and what critical gaps you need to address), and the proven strategies to lower your costs without sacrificing protection.
Quick look at homeowners insurance pembroke pines fl:
Understanding the Cost of Homeowners Insurance in Pembroke Pines FL
When we talk about the cost of homeowners insurance Pembroke Pines FL, it’s easy to feel overwhelmed. The numbers can be startling. The average cost of home insurance in Pembroke Pines typically ranges from $4,310 to $6,311 annually. This is significantly higher than Florida’s average rate of about $2,924 per year, making Pembroke Pines rates approximately 115% higher than the state average. For comparison, the national average for home insurance sits around $1,754.
Why such a difference? Pembroke Pines, like much of South Florida, faces unique risks. We’re in a region prone to hurricanes, tropical storms, and heavy rainfall. This geographical reality, combined with the increasing cost of rebuilding and repairing homes, drives premiums upward. In fact, home insurance costs in Broward County, where Pembroke Pines is located, have increased by a staggering 31% between 2022 and 2024 Broward county costs increased 31%.
Understanding these costs is the first step toward finding affordable and comprehensive coverage. To get a better grasp of what you might pay, we offer a handy Home Insurance Calculator on our site.
Key Factors That Influence Your Premium
Several factors are at play when calculating your homeowners insurance premium in Pembroke Pines. It’s not just about the size of your home; it’s a complex equation that considers everything from your home’s age to your personal financial history. Here’s a closer look at what influences your rates:
- Home Age and Construction: This is a big one in Florida. Older homes, especially those built before 2001, often have higher premiums. Why? Because homes built after 2001 generally meet updated building codes that make them more resistant to wind and water damage.
- Construction Materials: The materials used to build your home and its roof play a crucial role. Impact-resistant windows, concrete block construction, and hip roofs can lead to lower rates.
- Dwelling Coverage Amount: This refers to the cost to rebuild your home. Naturally, the higher the estimated rebuilding cost, the higher your premium will be.
- Claims History: If you’ve filed multiple claims in the past, insurers will view you as a higher risk, leading to increased rates. Conversely, a claims-free history can often result in discounts.
- Credit Score: In Florida, your credit score can impact your insurance rates. A higher credit score often signals financial responsibility, which can translate to lower premiums.
- Wind Mitigation Features: Features designed to protect your home from wind damage during hurricanes (like hurricane straps, roof-to-wall attachments, and impact-resistant openings) can significantly reduce your premiums, sometimes by up to 40%.
- Proximity to the Coast and Fire Hydrants: Homes closer to the coast face higher wind and flood risks. Similarly, homes further from fire hydrants or fire stations might have higher rates due to increased risk of fire damage.
- Location-Specific Risks: Beyond the general coastal proximity, your specific flood zone designation and local crime rates can also affect your premium.
The Impact of Dwelling Coverage and Home Age
The amount of dwelling coverage you choose and the age of your home are two of the most significant determinants of your homeowners insurance Pembroke Pines FL premium. It’s crucial to select adequate dwelling coverage to protect your investment, but understanding how it affects your cost is key.
Here’s a look at average annual premiums based on dwelling coverage amounts in Pembroke Pines:
- Dwelling Coverage $300,000 – $399,999: Around $4,077 annually.
- Dwelling Coverage $500,000 – $599,999: Approximately $5,194 annually.
- Dwelling Coverage $700,000 – $799,999: Roughly $6,131 annually.
As you can see, the cost increases with the amount of coverage needed to rebuild your home. It’s vital to ensure your dwelling coverage reflects the replacement cost of your home, not just its market value, as rebuilding can often be more expensive than what you paid for the property.
The age of your home also plays a dramatic role in your insurance costs. This is particularly true in Florida due to changes in building codes designed to withstand severe weather.
- Homes older than 25 years in Pembroke Pines have an average premium of $4,574.
- Newer homes (built within the last 25 years), especially those constructed post-2001, enjoy significantly cheaper rates, averaging around $2,861.
This difference stems from the Florida Building Code updates implemented after Hurricane Andrew in 1992, with significant improvements becoming mandatory around 2001. These codes require stronger construction methods, better roof-to-wall attachments, and more resilient materials, which translate to lower risk for insurers and, often, lower premiums for homeowners. If your home was built before these codes were in place, don’t despair! There are still ways to reduce your premiums, which we’ll discuss shortly.
What Your Policy Covers (And What It Doesn’t)
Understanding your homeowners insurance policy can feel like reading a foreign language. But know what protections you have in place and, just as importantly, what you don’t. A typical homeowners insurance Pembroke Pines FL policy is designed to protect your most valuable asset from a range of perils, but it’s not a one-size-fits-all solution, especially in Florida.
Most homeowners policies fall into categories like HO3 Insurance Policy or HO5 Insurance Policy Guide. An HO3 is the most common, offering “open peril” coverage for your dwelling (meaning it covers everything unless specifically excluded) and “named peril” coverage for your personal belongings (meaning it only covers risks explicitly listed). An HO5 offers “open peril” coverage for both your dwelling and personal property, providing broader protection.
What Does a Typical Homeowners Insurance Pembroke Pines FL Policy Cover?
A standard homeowners insurance policy in Pembroke Pines typically includes several key components, each designed to protect a different aspect of your home and finances:
- Dwelling Coverage (Coverage A): This covers the physical structure of your home, including the roof, walls, foundation, and attached structures like a garage. It protects against damage from covered perils such as fire, wind, lightning, and vandalism.
- Personal Property (Coverage C): This protects your belongings inside your home, such as furniture, electronics, clothing, and other valuables, from covered events like theft, fire, or wind damage.
- Other Structures (Coverage B): This covers detached structures on your property, such as sheds, detached garages, fences, or gazebos, from the same perils as your main dwelling.
- Loss of Use (Coverage D): Also known as Additional Living Expenses (ALE), this covers costs if your home becomes uninhabitable due to a covered loss. This can include temporary housing, meals, and other living expenses while your home is being repaired.
- Personal Liability (Coverage E): This provides financial protection if you or a family member are found legally responsible for injuries to others or damage to their property, whether it occurs on or off your premises. This coverage can help with medical bills, legal fees, and settlement costs.
- Medical Payments to Others (Coverage F): This covers medical expenses for guests injured on your property, regardless of who is at fault. It’s typically for smaller claims and aims to prevent liability claims.
These coverages protect against common perils like fire, wind (often with a separate hurricane deductible), lightning, theft, and certain types of water damage (e.g., from a burst pipe). However, there’s one significant peril that standard policies do not cover.
The Critical Difference: Homeowners vs. Flood Insurance
This is perhaps the most crucial distinction for any homeowner in Florida, especially in Pembroke Pines: standard homeowners insurance policies DO NOT cover flood damage. This is a common misconception that can lead to devastating financial consequences.
Given Florida’s susceptibility to hurricanes and heavy rainfall, flood insurance is not just recommended; it’s often essential. In 2024, FEMA added 22,000 properties in Pembroke Pines to their flood zone maps, meaning more homeowners are now identified as being in high-risk areas. If you have a mortgage and your home is in a high-risk flood zone, your lender will likely require you to carry flood insurance.
Here’s a quick comparison:
| Feature | Standard Homeowners Policy | Separate Flood Insurance Policy |
|---|---|---|
| What it covers | Damage from fire, wind, theft, certain water damage (e.g., burst pipes), liability | Damage directly caused by flooding (e.g., rising waters, storm surge) |
| Hurricane Wind Damage | YES (subject to hurricane deductible) | NO (wind damage is covered by homeowners policy) |
| Hurricane Flood Damage | NO | YES |
| Personal Property | YES (for covered perils) | YES (for flood damage, often separate coverage) |
| Additional Living Expenses | YES (for covered perils) | NO (typically not included) |
| Mandatory? | Often by lenders | If in high-risk flood zone with federally-backed mortgage |
Flood insurance can be purchased through the National Flood Insurance Program (NFIP) or through private flood insurance providers. We can help you explore both options to ensure your home is fully protected from rising waters. Don’t get caught off guard; a hurricane can bring both devastating winds and catastrophic flooding, and you need separate policies for each.
How to Lower Your Premiums and Save Money
The high cost of homeowners insurance Pembroke Pines FL can be daunting, but there are proactive steps you can take to significantly reduce your premiums without compromising on crucial coverage. Think of it as investing in your home’s resilience, which insurers reward with lower rates.
Available Discounts for Pembroke Pines Homeowners
Insurance companies offer various discounts designed to incentivize homeowners to reduce their risk exposure. Taking advantage of these can lead to substantial savings:
- Wind Mitigation Credits: This is perhaps the most impactful discount in Florida. If your home has features that reduce damage from high winds, such as roof-to-wall attachments, secondary water resistance, impact-resistant windows or hurricane shutters, or a hip roof, you can qualify for significant credits. These can sometimes reduce your premium by up to 40%, especially for older homes.
- Bundling Home and Auto Insurance: Many insurers offer a multi-policy discount when you purchase both your homeowners and auto insurance from the same company. This is a simple and effective way to save on both policies.
- Security and Fire Alarm Systems: Installing a monitored home security system, smoke detectors, and fire suppression systems (like sprinklers) can lead to discounts because they reduce the risk of theft and fire damage.
- Claims-Free History: Maintaining a good claims history, or even better, being completely claims-free for a certain period, can earn you a discount. This shows insurers you’re a lower risk.
- Higher Deductibles: Choosing a higher deductible (the amount you pay out-of-pocket before your insurance kicks in) will lower your annual premium. Just make sure you can comfortably afford your chosen deductible if you need to file a claim.
- New Home Discount: Newer homes often come with inherent discounts due to modern construction standards and materials.
- Senior Discount: Some providers offer discounts for homeowners over a certain age.
- Association Discounts: If you are part of certain professional organizations or alumni groups, you might be eligible for group discounts.
How to Lower Your Homeowners Insurance Pembroke Pines FL Premiums
Beyond just discounts, a few strategic moves can put more money back in your pocket:
- Upgrading Your Roof: An old or damaged roof is a major red flag for insurers. Replacing an aging roof with a new, hurricane-resistant one can make a huge difference in your premium. Insurers look for roofs with a longer lifespan and better wind resistance.
- Installing Impact-Resistant Windows and Doors: These upgrades not only protect your home from hurricane-force winds and flying debris but also deter burglars, making your home safer and potentially earning you discounts.
- Improving Your Credit Score: As mentioned earlier, a good credit score can positively impact your insurance rates in Florida. Pay your bills on time, reduce debt, and regularly check your credit report for errors.
- Shopping Around Regularly: Insurance rates are not static. They can change annually based on market conditions, your claims history, and even changes in your insurer’s risk assessment. We recommend shopping for quotes at least every year or two, or whenever you have a significant life event (like a home renovation or a new vehicle). Don’t just renew automatically!
- Choosing the Right Deductible: While a higher deductible lowers your premium, it’s a balancing act. Choose a deductible you’re comfortable paying out-of-pocket in the event of a claim. For example, a $2,500 deductible might save you hundreds annually compared to a $500 deductible, but ensure you have that $2,500 readily available.
- Reviewing Your Coverage Annually: Your home’s value, your belongings, and your personal circumstances change. An annual review with your agent ensures your coverage is still appropriate and you’re not overpaying for coverage you no longer need, or worse, underinsured for new assets.
Frequently Asked Questions about Pembroke Pines Home Insurance
We get a lot of questions from homeowners in Pembroke Pines, and rightfully so! The insurance landscape here can be complex. Here are some of the most common inquiries we address:
Is homeowners insurance required in Pembroke Pines, FL?
No, homeowners insurance Pembroke Pines FL is not legally required by the state of Florida. However, if you have a mortgage on your home, your lender will almost certainly require you to carry a policy. This is because the lender has a financial interest in your property and wants to protect their investment. Even if you own your home outright, having homeowners insurance is a wise financial decision. It protects your most significant asset from unforeseen damages and provides crucial liability protection, safeguarding your financial future from costly lawsuits.
How much dwelling coverage do I need?
Determining the right amount of dwelling coverage is critical. It should reflect the replacement cost of your home, which is the amount it would cost to rebuild your home from the ground up after a total loss, using similar materials and quality. This is often different from your home’s market value (what you could sell it for), which includes the land value and takes into account factors like location and current real estate trends.
We always recommend using a reliable Home Insurance Calculator and, more importantly, consulting with an experienced insurance agent. An agent can help you accurately assess rebuilding costs in your specific area, considering local construction expenses and material availability, ensuring you aren’t underinsured or overinsured.
Does my policy cover hurricane damage?
This is a nuanced question for Florida homeowners. A standard homeowners insurance Pembroke Pines FL policy typically covers wind damage caused by a hurricane. However, it’s crucial to understand that these policies usually come with a separate hurricane deductible, which is often a percentage (e.g., 2%, 5%, or even 10%) of your dwelling coverage amount, rather than a flat dollar amount. This deductible applies specifically to damage caused by named hurricanes.
What your standard policy does not cover is flood damage resulting from a hurricane. This includes damage from storm surge, heavy rainfall leading to rising waters, or overflowing bodies of water. For flood damage, you need a separate flood insurance policy. For a more in-depth look at hurricane preparedness and insurance, our Key West Home Insurance Ultimate Guide offers valuable insights, many of which apply to other coastal regions of Florida.
Find the Right Pembroke Pines Coverage Today
Navigating the complexities of homeowners insurance Pembroke Pines FL can feel like a full-time job. With fluctuating rates, specific Florida risks, and the need to balance comprehensive coverage with affordability, it’s easy to get lost in the details. That’s where we come in.
As a Florida-based insurance broker, we at Forever Florida Insurance are dedicated to making insurance simple, secure, and reliable for Floridians. We understand the unique challenges faced by homeowners in Pembroke Pines and across the state, from hurricane season to updated flood zones. Our local focus means we’re not just selling policies; we’re building relationships and protecting our neighbors.
We work with over 30 top-rated insurance carriers, allowing us to shop the market on your behalf. This means we can compare a wide range of options, identify all eligible discounts, and help you secure a policy that truly fits your needs and budget. Our goal is to provide you with peace of mind, knowing that your home and family are protected without you getting flooded with unnecessary fees or inadequate coverage.
Don’t leave your biggest investment to chance. Let us help you find the right homeowners insurance Pembroke Pines FL today.
Ready to secure your home and your peace of mind?
Get a personalized home insurance quote with us now! For all your personal insurance needs, explore our Personal Insurance options.