
Why Every Florida Business Owner Needs Comprehensive Insurance Coverage
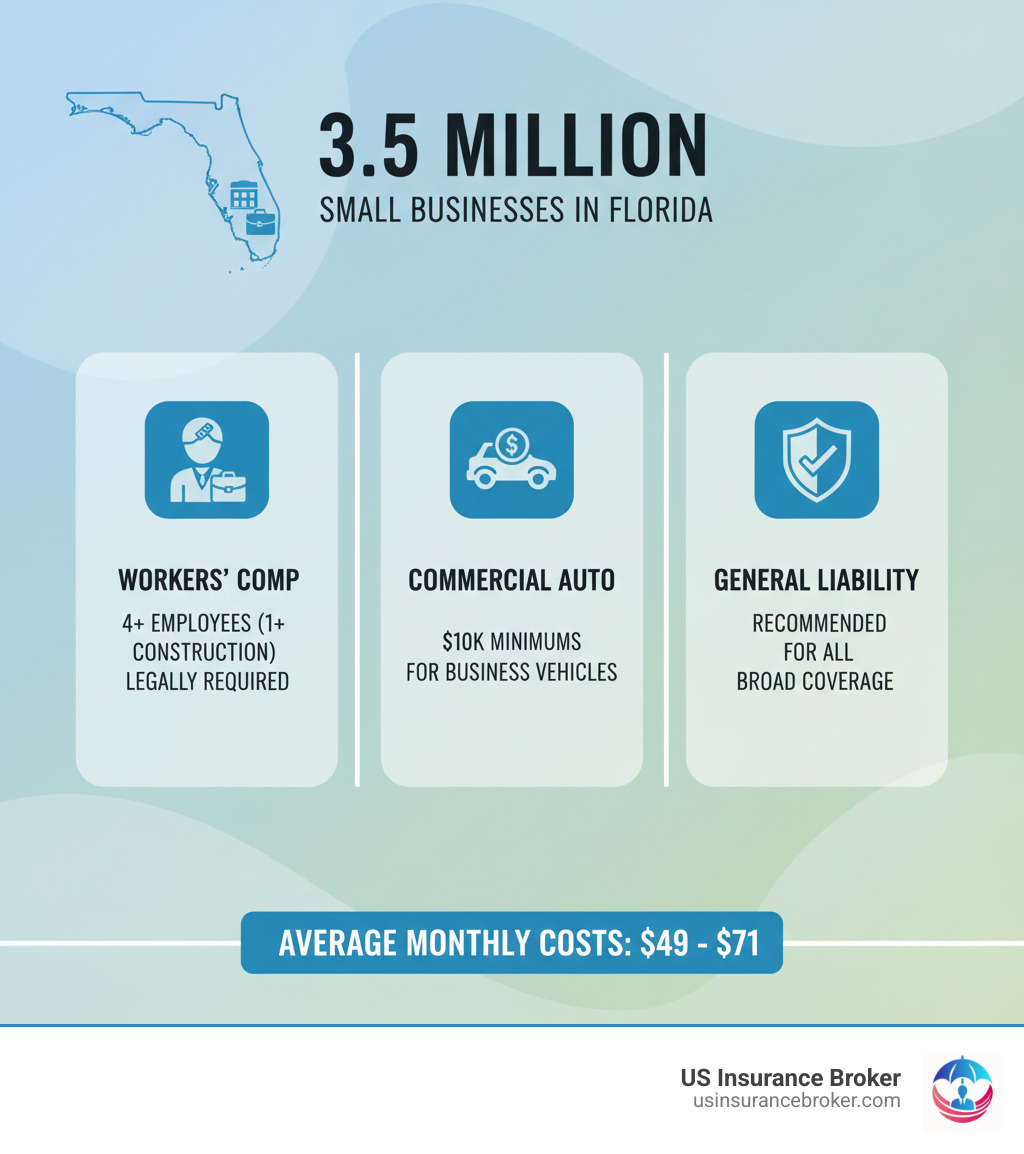
Florida business insurance is essential for the state’s 3.5 million small businesses. While Florida law only mandates a few policies, most businesses need several types of coverage to protect against the unique risks of operating here—from hurricanes and flooding to liability claims and cyber threats.
Key Florida Business Insurance Takeaways:
- Legally Required: Workers’ Compensation (4+ employees, 1+ for construction) and Commercial Auto Insurance (for business-owned vehicles).
- Highly Recommended: General Liability Insurance, Commercial Property Insurance, and a Business Owner’s Policy (BOP).
- Average Monthly Costs: General Liability ~$49, Workers’ Comp ~$54, Professional Liability ~$71.
- Critical Considerations: Hurricane exposure, coastal premiums, flood coverage exclusions, and cyber liability.
Running a business in Florida means facing unique risks. A customer slip-and-fall, a hurricane shutdown, or an employee injury can lead to devastating costs. Without proper coverage, a single incident could threaten your entire operation. Standard policies often exclude Florida’s biggest threats, like flood damage, and coastal businesses face higher premiums due to hurricane exposure.
As the owner of Forever Florida Insurance, I’ve helped countless Florida business owners steer this complex landscape. This guide will walk you through the coverage you need, what it costs, and how to secure the right policies for your business.
Explore more about Florida business insurance:
Legally Required vs. Recommended Florida Business Insurance
Understanding which insurance is required versus recommended is key. While Florida law mandates very little, smart business owners know that “recommended” coverage is essential for proper protection against risks like hurricanes and liability claims.
State-Mandated Insurance Policies
Florida law requires two types of Florida business insurance, and they are non-negotiable.
Workers’ Compensation Insurance is required for most employers. For construction businesses, you need coverage for even one employee. For all other industries, the requirement starts at four or more employees (full-time or part-time). This policy covers medical bills, rehabilitation, and lost wages for employees who get sick or injured on the job. It also protects you from lawsuits by injured workers. Failing to carry this coverage can lead to steep fines and legal trouble. For official details, see the Florida Workers’ Comp requirements or our plain-English FL Workers Comp Coverage guide.
Commercial Auto Insurance is required for any business that owns, leases, or uses vehicles for work. Under Florida’s “no-fault” system, the minimums are $10,000 for property damage liability and $10,000 for Personal Injury Protection (PIP) per accident. Be aware that a personal auto policy likely won’t cover accidents that happen during business use. A commercial policy or “hired and non-owned auto” coverage is crucial. Learn more with our Commercial Auto Insurance guide.
Highly Recommended Insurance for Florida Businesses
These policies aren’t legally required but are vital for protecting your business from common, everyday risks.
General Liability Insurance is the foundation of business protection. It covers legal costs, medical expenses, and settlements for third-party claims of bodily injury, property damage, and personal/advertising injury (like libel or slander). Most commercial landlords require proof of this coverage before you can sign a lease. Our General Liability Insurance Complete Guide explains this coverage in detail.
Commercial Property Insurance is critical in Florida due to our weather. It protects your physical assets—your building, equipment, inventory, and tools—from perils like fire, theft, and wind damage. For businesses near the Gulf Coast, this is survival insurance against hurricanes. Without it, you’re gambling your business on the weather. Explore the details in our Commercial Property Insurance guide and the state’s Commercial Property Insurance Overview from Florida’s DFS.
A Business Owner’s Policy (BOP) is a smart, cost-effective option that bundles general liability, commercial property, and business interruption insurance into one package. Business interruption coverage is especially valuable, as it replaces lost income if a covered event like a hurricane forces you to close temporarily. Bundling these policies is typically cheaper than buying them separately and simplifies your insurance management. Our Business Owners Policy details page explains how a BOP can save you money.
Understanding the Cost of Business Insurance in Florida
The cost of Florida business insurance varies widely, as premiums depend on a unique combination of factors specific to your business and its location.
Key Factors Influencing Your Premiums
Insurers consider several factors when calculating your premiums:
- Industry: High-risk professions, like roofing, naturally pay more than low-risk ones, like graphic design.
- Location: This is a massive factor in Florida. A business on the coast in Tampa or Clearwater will pay significantly higher property insurance premiums than one inland due to hurricane exposure. Coastal businesses can pay double or triple what inland businesses pay.
- Business Size: More employees, higher revenue, and more assets to protect all translate to higher premiums. Your number of employees and total payroll directly impact workers’ compensation costs.
- Annual Revenue: Higher revenue suggests greater scale and exposure to risk.
- Coverage Limits & Deductibles: Higher coverage limits cost more, while a higher deductible (your out-of-pocket cost per claim) can lower your premium.
- Claims History: A history of frequent or expensive claims will increase your rates.
Average Costs for Florida Business Insurance
While costs are highly specific, here are some average monthly figures for common Florida business insurance policies for small to medium-sized businesses:
| Policy Type | Average Monthly Cost in Florida |
|---|---|
| General Liability | $49 |
| Workers’ Compensation | $54 |
| Professional Liability (E&O) | $71 |
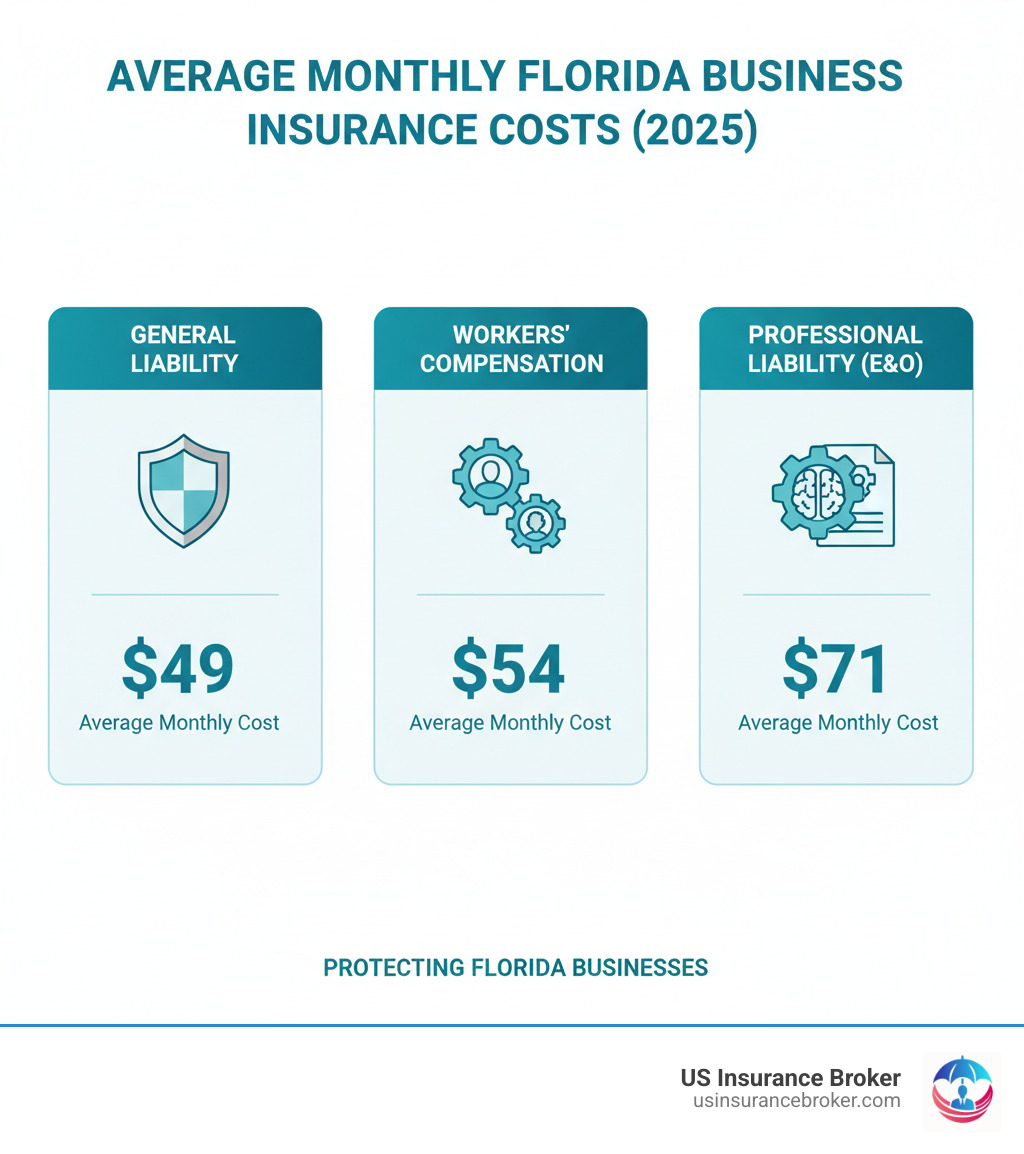
These are just averages. A low-risk inland business might pay less, while a high-risk coastal company could pay much more. Property insurance premiums show the most variability; a coastal business might pay $300-$500 monthly, while a similar inland business pays $100-$150. The only way to know your actual cost is to get a personalized quote.
Specialized Coverage for Modern & Industry-Specific Risks
Beyond the basics, Florida businesses need specialized policies to protect against modern digital threats and unique local challenges.
Protecting Against Professional & Digital Threats
If your business provides services, gives advice, or handles data, you need to look beyond traditional insurance.
Professional Liability Insurance, or Errors & Omissions (E&O) Insurance, protects you if a client claims your professional services caused them a financial loss due to negligence, errors, or omissions. For many Florida professionals like architects and accountants, this coverage is essential for protecting your business and reputation. Learn more in our Errors and Omissions explained guide.
Cyber Liability Insurance is now essential for nearly every business. Cybercriminals are three times more likely to target small businesses, which often have fewer defenses. A data breach can lead to costly notification expenses, legal fees, credit monitoring, and reputational damage. This policy covers these costs, providing a financial lifeline after a digital disaster.
Directors & Officers (D&O) Insurance safeguards the personal assets of your company’s directors and officers if they are sued for alleged wrongful acts in their management roles. Lawsuits can come from shareholders, employees, or regulators. D&O insurance allows your leadership to make critical decisions without fear of personal financial ruin. Our Directors and Officers Insurance guide explains how it works.
Navigating Florida’s Unique Environmental & Industry Challenges
Florida’s environment and diverse economy create special risks that require custom protection.

Hurricane and flood coverage is a complex but critical part of Florida business insurance. A crucial fact is that standard commercial property policies almost always exclude flood damage. Given Florida’s geography, separate flood insurance—often from the National Flood Insurance Program or a private insurer—is essential. Also, be aware of windstorm deductibles, which are typically a percentage (e.g., 2-5%) of your property’s insured value, meaning a high out-of-pocket cost. For more, see the Commercial Property Insurance Overview from Florida’s DFS.
Industry-specific policies are also necessary.
- Contractors need specialized coverage for tools, equipment, and job site liabilities. Our Contractor Insurance Florida guide has the details.
- Lawn care services face risks from equipment theft to property damage. Protect your business with the right policy, as explained in our Lawn Care Insurance Florida resource.
- Charter boat operations require marine-specific insurance for the vessel, passengers, and crew. Our Charter Boat Insurance Florida Guide covers what you need.
- Landlords need specialized Landlord Insurance to cover risks from tenant-caused damage to liability claims.
How to Get the Right Florida Business Insurance Policy
Securing the right coverage in Florida is straightforward when you have the right information and expert guidance. At Forever Florida Insurance, we make the process simple, secure, and reliable.
The Process of Obtaining a Quote
Getting an accurate quote for Florida business insurance is the first step. To help us find the best options for your needs, please have the following details ready:
- Business legal name and physical address
- Description of your industry and daily operations
- Estimated annual revenue and total annual payroll
- Number of employees
- Any past claims history
- The types of coverage you’re interested in
With this information, we can quickly assess your risks and find suitable options. Ready to start? Request a Business Insurance Quote or Get a Quote today.
Choosing Your Provider: Independent Agent vs. Direct Carrier
You can buy Florida business insurance directly from a carrier or work with an independent agent. Going direct limits you to one company’s products. An independent agent, like us, shops multiple carriers to find the best fit for you.
As a Florida-based broker, we offer:
- Access to multiple carriers to compare policies and prices.
- Unbiased advice focused on your business’s needs.
- Local expertise on Florida’s unique risks, from hurricanes to industry regulations.
- Customized policies that provide true protection.
It’s also important to know the difference between admitted and surplus lines insurers. Admitted insurers are regulated by Florida, follow state-approved rates, and are backed by the Florida Insurance Guaranty Fund. Surplus lines insurers cover unique or high-risk businesses that admitted carriers may decline. They offer more flexibility but lack the guaranty fund’s protection. We can help you determine which is right for you.
Reliable Resources for Florida Business Owners
Stay informed with these reliable resources:
- The Florida Department of Financial Services (DFS) offers official state information, including tools to verify an agent’s license and look up insurance companies.
- The U.S. Small Business Administration (SBA) provides valuable resources, such as the 2023 Florida Small Business Profile.
- Forever Florida Insurance offers local support and expertise. Visit our About Us page or read our Blog for more information on Business Insurance.
Frequently Asked Questions about Florida Business Insurance
Here are answers to common questions we hear from Florida business owners.
How much does a $1 million general liability policy cost in Florida?
The cost isn’t a fixed number. On average, a $1 million general liability policy in Florida might cost between $500 to $1,200 per year ($42 to $100 per month). However, this range can shift significantly based on your specific risk factors.
Your industry, location, annual revenue, number of employees, and claims history all influence the final premium. A low-risk consultant will pay less than a high-risk roofer. The only way to know your actual cost for Florida business insurance is to get a personalized quote.
Do I need business insurance for a home-based business in Florida?
Yes, absolutely. A standard homeowners policy specifically excludes coverage for business-related activities and liabilities. If a client is injured at your home office, or if your business equipment is stolen or damaged, your homeowners insurance likely won’t cover the loss.
You need a separate Florida business insurance policy to protect against business liability, cover your equipment, and manage other risks associated with your operation, even if it’s run from home. We can help you find affordable coverage to fill these critical gaps.
What is a certificate of insurance (COI) and why do I need one?
A Certificate of Insurance (COI) is a one-page document that summarizes your insurance coverage, including policy types, limits, and effective dates. It serves as proof of insurance.
You will likely need a COI to:
- Sign contracts with clients, who want to ensure you’re covered.
- Lease commercial space, as landlords almost always require it.
- Prove compliance with contractual insurance requirements.
A COI shows professionalism and gives partners peace of mind. Once your policy is active, we can provide a COI quickly whenever you need one.
Conclusion
Running a business in the Sunshine State means accepting that some risks, like hurricanes and liability claims, come with the territory. You can’t control when a disaster will strike, but you can control how prepared you are. That preparation begins with having the right Florida business insurance in place.
Comprehensive protection is what stands between your business and a potential financial disaster. It’s not about buying every policy available, but about making informed decisions to cover your specific vulnerabilities.
At Forever Florida Insurance, we make this process simple. As a Florida-based company, we understand the local risks you face. We listen to your concerns, assess your unique situation, and connect you with coverage that makes sense for your business—without the jargon or pressure.
The best time to get insured was yesterday. The second-best time is now, before you need it. For a personalized assessment and to explore solutions custom to your Florida business, visit our Business Insurance page. Let’s work together to keep your business protected.