
Why Florida Contractor Liability Insurance is Non-Negotiable for Your Business
Florida contractor liability insurance is a legal requirement for licensed contractors, protecting your business from property damage and bodily injury claims while ensuring you meet state licensing mandates.
Required Minimum Coverage by Contractor Type:
- General & Building Contractors: $300,000 bodily injury / $50,000 property damage
- Residential & Specialty Contractors: $100,000 bodily injury / $25,000 property damage
- Alternative: Combined single-limit policy of $800,000
What You Must Do:
- Obtain public liability and property damage insurance before license issuance.
- Submit a signed affidavit and Certificate of Insurance (COI) to the Construction Industry Licensing Board.
- Maintain continuous coverage for your active license.
Florida’s construction boom brings significant risk. A single lawsuit could be financially devastating, with the average customer injury claim costing $35,000. Beyond financial risk, Florida law makes this insurance a prerequisite for licensing. The state conducts random audits, and non-compliance can lead to license suspension, fines, and an inability to pull permits.
Navigating these requirements doesn’t have to be complicated. I’m William Kane II, owner of Forever Florida Insurance. I help Florida contractors understand their needs and secure comprehensive, affordable florida contractor liability insurance. With access to 30+ carriers, my team provides clear advice to protect your business, letting you focus on your work.
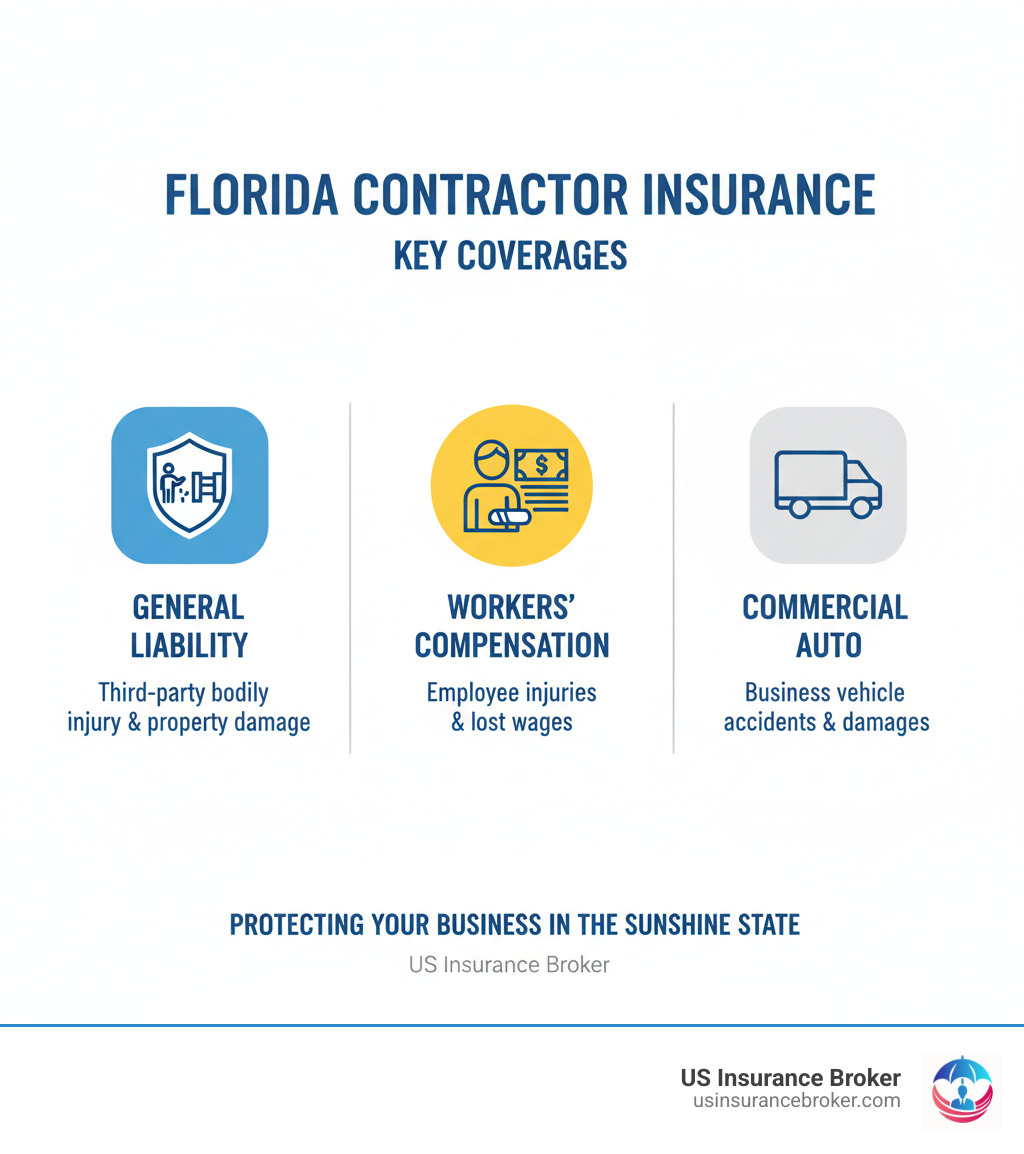
Florida contractor liability insurance terms to remember:
Understanding Florida Contractor Liability Insurance Requirements
To get a contractor’s license in Florida, you must prove you’re protected. The Florida Department of Business & Professional Regulation (DBPR) and its Construction Industry Licensing Board (CILB) mandate Florida contractor liability insurance. You cannot get or renew a license without it, and the CILB conducts random audits to ensure compliance.
The consequences of a coverage lapse are severe: license suspension or revocation, steep fines, and the inability to pull permits or bid on projects. An insurance gap can halt your business overnight. We help Florida contractors understand the official Public Liability Insurance rules and secure the right coverage without confusion.
Minimum Liability Limits for Florida Contractors
Florida sets minimum coverage limits based on your license type.
General and Building Contractors need the highest coverage: $300,000 for bodily injury and $50,000 for property damage. Residential and Specialty Contractors (including roofing, plumbing, HVAC, and other trades) must carry at least $100,000 for bodily injury and $25,000 for property damage.
Here’s the complete breakdown:
| Contractor Type | Bodily Injury / Public Liability | Property Damage |
|---|---|---|
| General Contractor | $300,000 | $50,000 |
| Building Contractor | $300,000 | $50,000 |
| Residential Contractor | $100,000 | $25,000 |
| Specialty Contractor | $100,000 | $25,000 |
| Sheet Metal Contractor | $100,000 | $25,000 |
| Air Conditioning Contractor | $100,000 | $25,000 |
| Roofing Contractor | $100,000 | $25,000 |
| Mechanical Contractor | $100,000 | $25,000 |
| Pool Contractor | $100,000 | $25,000 |
| Plumbing Contractor | $100,000 | $25,000 |
| Underground Utility & Excavation | $100,000 | $25,000 |
| Solar Contractor | $100,000 | $25,000 |
| Pollutant Storage System | $100,000 | $25,000 |
As an alternative, you can get a combined single-limit policy of $800,000. Meeting these minimums is mandatory to operate legally. For more on the licensing process, the Florida DBPR offers details on state licensing.
The Role of the Certificate of Insurance (COI)
Your Certificate of Insurance (COI) is your proof of coverage. The CILB requires it for licensing and renewal, but its importance extends further. Clients, landlords, and lenders all demand a COI to ensure you’re protected before they will work with you.
A valid COI must include your business name, policy number, effective dates, and coverage amounts. Crucially, it must list the “State of Florida, Department of Business and Professional Regulation, Construction Industry Licensing Board” as the certificate holder and include a 30-day cancellation notice clause. We ensure your COI is accurate and ready when you need it, preventing delays and compliance issues.
Decoding Your Liability Coverage: What’s Included and Excluded?
Florida contractor liability insurance provides financial protection against third-party claims and lawsuits arising from accidents. This coverage is a core part of any contractor’s Business Insurance plan.
What is florida contractor liability insurance?
Often called Commercial General Liability (CGL), this insurance responds when a third party claims your business caused them bodily harm or damaged their property. For a full overview, see our General Liability Insurance Ultimate Guide.
Key coverages include:
- Bodily Injury Coverage: Covers medical and legal costs if a non-employee (like a client or visitor) is injured at your job site.
- Property Damage Coverage: Pays for repairs or replacement if you accidentally damage someone else’s property, like a client’s car or a neighbor’s window.
- Personal and Advertising Injury: Protects against claims of libel, slander, or copyright infringement in your marketing.
- Medical Payments: Covers minor medical expenses for injuries on your premises, regardless of fault, which can help prevent larger lawsuits.
- Completed Operations Coverage: This is vital for contractors, as it covers claims for injury or damage that occur after you’ve finished a project. For example, if a railing you installed fails months later, this coverage would respond. As seen in this general liability insurance example, this protection can be a business-saver.
Common Exclusions in a General Liability Policy
Understanding what your policy doesn’t cover is just as important. Common exclusions include:
- Intentional Acts: Damage or injury caused on purpose.
- Professional Errors: Mistakes in design, advice, or professional services (covered by a separate policy).
- Employee Injuries: These are covered by workers’ compensation insurance.
- Auto Accidents: Incidents involving business vehicles require a commercial auto policy.
- Contractual Liability: Certain risks you assume via a contract may be excluded.
- Pollution: Damage from pollutants like chemical spills often requires specialized coverage.
- Damage to Your Own Property: Your tools, equipment, and business property are not covered by general liability.
Knowing these exclusions helps identify gaps where additional insurance may be needed for comprehensive protection.
Beyond the Basics: Essential Insurance Policies for Florida Contractors
While florida contractor liability insurance is the bedrock, a complete risk management strategy requires layering other policies to protect your crew and assets. Bundling policies into a Business Owners Policy (BOP), which combines general liability and commercial property insurance, can be an efficient and cost-effective option for many Florida contractors.
Workers’ Compensation Insurance
In Florida, Workers Comp Insurance is legally required for contractors with one or more employees. This policy protects your business and your team if an employee gets hurt or sick on the job. It covers their medical bills, rehabilitation, and a portion of lost wages. It also shields your business from employee-injury lawsuits. For more information, see our guides on Florida’s workers’ compensation requirements and what to do if an employee is injured at work in Florida.
Commercial Auto, Builder’s Risk, and Surety Bonds
Several other policies are crucial for Florida contractors:
- Commercial Auto Insurance: If your business owns vehicles, this is a must-have in Florida. It covers accidents involving your work trucks or vans. Learn more in our guide to Commercial Auto Insurance.
- Builder’s Risk Insurance: Also known as course of construction insurance, this policy protects projects while they are under construction. It covers the structure and on-site materials from perils like fire, theft, and natural disasters—a key concern in Florida.
- Surety Bonds: Often required for public projects, these are not traditional insurance but guarantees. A performance bond, for example, guarantees you will complete the project as contracted. They provide financial assurance to the project owner.
Professional Liability (E&O) Insurance
General liability doesn’t cover claims from professional mistakes. For that, you need Professional Liability, or Errors and Omissions (E&O), insurance. This is vital for contractors who provide design, consulting, or advisory services. It covers financial losses a client suffers due to your professional errors, omissions, or negligence. As this overview of professional liability insurance explains, it’s essential for design-build firms and those offering expert advice.
Managing Costs and Getting the Right Coverage
At Forever Florida Insurance, we make finding affordable Florida contractor liability insurance simple. We provide no-obligation quotes and clear advice to help you protect your business without overspending. While the average cost for general liability is around $114 per month, your actual premium will depend on several factors.
Factors Influencing the Cost of Florida Contractor Liability Insurance
The cost of your policy is influenced by:
- Type of Work: Higher-risk trades like roofing or demolition typically have higher premiums than lower-risk trades like painting.
- Business Size: Your number of employees, annual revenue, and project scale affect your premium.
- Claims History: A clean record helps keep costs down, while frequent claims can increase them.
- Location: Operating in areas with higher population density or risk of natural disasters, like parts of the Gulf Coast, can impact rates.
- Coverage Limits and Deductibles: Higher limits increase premiums, while a higher deductible can lower them.
- Subcontractor Use: Insurers will verify that your subcontractors are properly insured to minimize your liability.
We specialize in finding custom-fit policies for contractors in Tampa Bay and surrounding areas. Start with a Business Insurance Quote for a personalized estimate.
How to Compare Quotes and Secure Your Policy
We simplify the process of securing the right Florida contractor liability insurance.
- Gather Your Business Details: Have your revenue, payroll, and insurance history ready for accurate quotes.
- Work with an Agent: As brokers with access to over 30 carriers, we shop the market for you to find the best combination of coverage and price.
- Compare Limits and Deductibles: We’ll help you analyze different policy options to ensure they align with your risk tolerance and project requirements.
- Review Policy Documents: We walk you through the fine print, explaining what is and isn’t covered, so you have no surprises.
Ready to get started? Visit our Get a Quote page. We are committed to making insurance simple and reliable for Florida contractors.
Frequently Asked Questions about Florida Contractor Insurance
Here are answers to common questions about Florida contractor liability insurance.
What are the consequences of not having adequate contractor insurance in Florida?
Operating without proper insurance carries severe risks:
- License Suspension/Revocation: The Florida CILB conducts audits and will penalize non-compliant contractors.
- Fines and Work Stoppage: You can face substantial fines and will be unable to pull permits, halting all work.
- Personal Liability: Without insurance, you are personally responsible for all costs related to third-party injury or property damage claims, which can be financially devastating.
- Lost Business: Most clients, especially for larger projects, require proof of insurance before hiring a contractor.
Does general liability cover faulty workmanship?
No, general liability insurance typically does not cover the cost to fix your own faulty work. However, it often covers the resulting damage caused by that faulty work. For example, if a poorly installed pipe bursts and damages a client’s floor, the policy would cover the floor damage but not the cost to re-install the pipe. Completed operations coverage extends this protection after the job is done, but it still only covers resulting damage. Claims related to professional design errors require a separate Professional Liability (E&O) policy.
How is workers’ compensation different from general liability?
These two essential policies cover different groups and risks.
- Workers Comp Insurance protects your employees. It is required by Florida law for employers and covers medical bills and lost wages for work-related injuries.
- General Liability protects third parties. It is required for state licensing and covers claims from non-employees (like clients or visitors) for bodily injury or property damage.
In short, workers’ comp is for your team, while general liability is for everyone else. Both are non-negotiable for a protected contracting business in Florida.
Conclusion
Navigating Florida contractor liability insurance is a critical step for any successful contracting business in the state. It’s about more than legal compliance; it’s about building a strong foundation for your livelihood and gaining peace of mind.
This guide covered the essentials: mandatory state licensing requirements, what general liability includes (and excludes), and other vital policies like workers’ compensation, commercial auto, builder’s risk, and professional liability.
Your insurance needs are unique, shaped by your specific work, business size, and location. A “one-size-fits-all” policy is not enough; you need custom coverage that truly protects you.
At Forever Florida Insurance, we make insurance simple, secure, and reliable for Florida contractors. We untangle the complexities and connect you with the exact coverage you need. Let us be your guide, protecting your business so you can build with confidence.
Don’t leave your hard work exposed to risk. Let us help you build a solid foundation of protection for your contracting business. Contact us to secure your business insurance today!